

Affirm: Buy now, pay over time
by Affirm, Inc
4.8
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
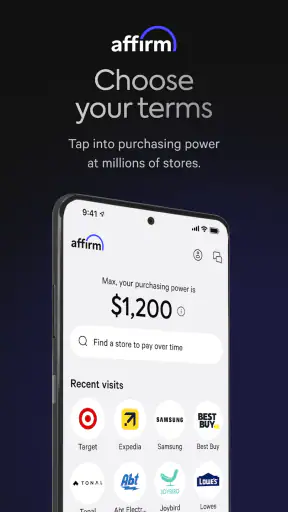
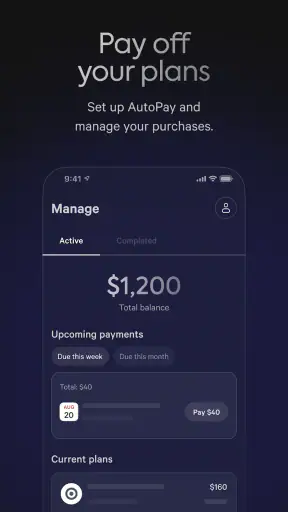
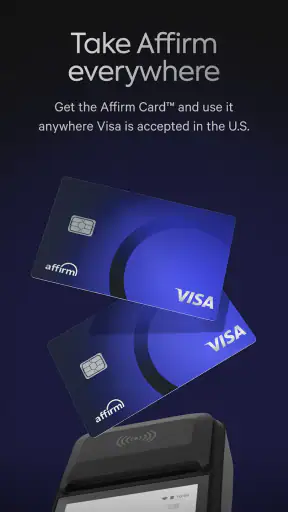
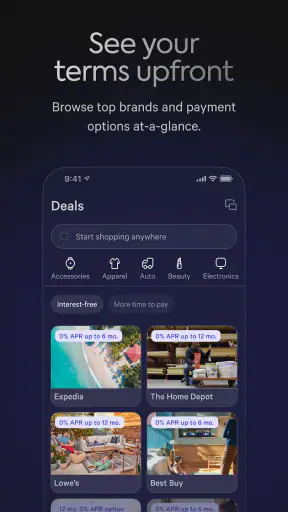
 Analysis by Getfullapps
When I shop online, I usually want two things at once: a clear view of the total cost and a payment choice that does not make the checkout process feel unnecessarily complicated. Affirm: Buy now, pay over time is built around that decision. It is a free shopping app from Affirm, Inc that lets me explore flexible payment options and look for savings before completing a purchase. I see it as a tool for planning a larger expense rather than as a reason to buy something I cannot reasonably afford.
My first impression is that the app makes the payment side of shopping easier to understand than a traditional credit-card checkout can be. Instead of treating financing as an afterthought, it puts the repayment choice close to the purchase decision. That can be useful for furniture, electronics, travel-related spending, or another planned item where spreading the cost fits my budget better than paying everything immediately. It is less convincing for small impulse purchases, where adding another payment commitment may create more work than value.
How Affirm feels in everyday shopping
I find Affirm most useful when a purchase is already planned and I want to pause before deciding how to pay, rather than treating checkout as the moment to figure everything out. That pause gives me room to compare a payment schedule with paying upfront and to ask whether the item fits my budget at all. The next section looks at how I would check the choices and keep the decision under my control.
A quick start, with the important details still worth reading
The app is presented as a shopping companion, but its real value appears when I slow down and examine the payment terms attached to a particular purchase. The interface is intended to help me move from browsing to a payment option, so the early experience feels more focused than using a general shopping marketplace. I would not install it expecting an enormous catalog of unrelated products; I would install it to make a planned purchase easier to evaluate financially.
Speed matters here because nobody wants to spend several minutes waiting just to discover whether a payment option is available. In normal use, I would expect the opening screens and basic browsing to feel reasonably direct on a supported device, although the exact experience can depend on the phone, connection, and the checkout flow involved. The app may feel quick when I am simply reviewing information, while a purchase decision can naturally take longer because there are more details to inspect.
That distinction is important. A fast screen transition does not automatically mean a good financing experience. I pay more attention to whether the total repayment, schedule, and conditions are understandable before confirming anything. The most useful speed improvement is not rushing through checkout; it is finding the relevant payment information without hunting for it.
Where the app helps during a larger purchase
A realistic example would be replacing a broken laptop when my next paycheck is already allocated to rent and household bills. I could use the app to investigate whether splitting the expense makes sense, then compare that plan with paying by debit card, using a regular credit card, or waiting until I have the full amount. In that situation, the app gives me a dedicated place to think through the purchase instead of making the decision entirely inside a retailer’s checkout page.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also find the planning angle more valuable than the phrase “buy now” suggests. Before I commit, I would write down the full amount I can comfortably devote to the purchase each month, including existing obligations. Then I would compare that personal limit with the schedule shown in the app. This prevents a low-looking periodic payment from disguising the fact that several other commitments may already be active.
One practical habit is to open the app before I am standing at the final checkout button. That gives me time to read the offer calmly, check whether the purchase is genuinely necessary, and decide whether the flexibility is worth accepting another scheduled payment. It also makes the app more useful as a budgeting aid and less like a last-second temptation.
Heavy-use moments and what to watch
The busiest moments are likely to come when I am comparing several purchases, revisiting payment choices, or moving between the app and a retailer’s checkout. This is where a shopping-finance app can feel less effortless than a normal product browser. I may need to keep track of which item I was considering, which payment option applied, and whether the final checkout amount matches what I expected.
For that reason, I would avoid opening multiple purchase flows casually. A cleaner workflow is to choose one item, record its full price, inspect the available schedule, and only then move to the next option. This reduces the chance of confusing one planned payment with another. It is a small habit, but it matters more than simply having a fast interface.
Another useful tip is to take a moment to review the repayment calendar after making a decision. I would add those future payments to the same budgeting system I use for bills, rather than relying only on memory or on opening the app again later. The app can organize the payment choice, but my wider budget still needs to account for it.
Heavy use can also expose a trade-off between convenience and attention. The more purchases I manage through a flexible-payment service, the more important it becomes to keep a single overview of my obligations. I would not treat the app as a replacement for a bank statement or personal budget. It is better viewed as one payment-management tool inside a broader routine.
Stability, recovery, and confidence during checkout
For a finance-related shopping app, reliability means more than avoiding crashes. I want to know where I am in the process, whether an action was accepted, and what I should do if the connection drops at an inconvenient moment. I would be especially cautious about tapping a confirmation button repeatedly after a slow response. When money is involved, uncertainty is more stressful than a few extra seconds of loading.
If the app becomes unresponsive during a purchase, my preferred recovery method would be simple: stop tapping, check whether the order or payment action has already gone through, and reopen the relevant screen before trying again. I would also keep the retailer’s order confirmation and any payment information together. That approach is useful because it avoids turning a temporary delay into duplicate actions or unnecessary confusion.
The app’s strong public reception suggests that many people find it dependable enough for regular use. It holds an average rating of 4.8 from roughly 565 thousand ratings, and its audience has grown beyond 10 million installs. Those figures do not guarantee that every device or checkout will behave perfectly, but they do make the product feel established rather than experimental.
I also appreciate that the developer is clearly identified as Affirm, Inc. That gives the app a more direct identity than an anonymous payment utility, which matters when I am deciding where to review purchase terms and manage a commitment. Still, I would judge reliability by the clarity of each transaction as well as by the app’s reputation. A smooth login is useful, but a clear record of what I agreed to is more important.
Device limits and resource expectations
Affirm supports devices running at least OS version 10, so compatibility is not aimed at very old software. Before installing, I would check the operating system on an older phone rather than assuming every handset can run the current release. The current version is 4.81.3, which indicates that the app is actively maintained as a modern product, but an update can still feel different depending on the device and system environment.
I would expect a shopping and payment app to be less demanding than a game that renders complex graphics, but I would not make precise claims about battery use, storage, or background activity without testing the same version across different phones. My practical advice is to keep the operating system and app current, maintain enough free storage for normal updates, and avoid making an important purchase while the phone is already struggling with several demanding tasks.
Older hardware may show its limits during transitions between shopping pages, authentication, and checkout, particularly if the connection is also unstable. That does not necessarily mean the app is poorly designed; it may simply mean that financial transactions require more steps than ordinary browsing. On a newer supported phone, I would expect the experience to feel more comfortable, while on an aging device I would allow extra time and verify each result.
There is also a human device constraint: notifications and scheduled payments can become easy to overlook when a phone is crowded with alerts. I would keep the app available for reference but avoid depending on a notification alone as my financial reminder. A calendar entry or budget note gives me a second layer of awareness and remains useful even when I am not actively using the app.
How it compares with ordinary payment alternatives
A normal credit card is often simpler when I already have the available balance, understand its terms, and want one familiar statement. A debit card is more direct still, because the money leaves my account immediately and there is no separate repayment schedule to monitor. For a purchase I can comfortably pay today, those options may be less complicated than opening a flexible-payment plan.
Affirm becomes more interesting when timing matters. If a necessary purchase would disrupt my cash flow but can be handled responsibly through a clearly understood schedule, having a dedicated app for that choice can be more transparent than improvising with several cards. The advantage is not that delayed payment makes an item cheaper; the advantage is the ability to evaluate a structured option before committing.
Compared with a retailer’s own financing page, the app offers a more focused place to consider Affirm-related payment choices across shopping situations. The trade-off is that I may be moving between two experiences: the retailer where I select the item and the payment service where I review the plan. That extra step is acceptable when it improves my understanding, but not when I am only buying something inexpensive.
I would also compare the app with simply saving first. Saving avoids another scheduled obligation and is the better option when the purchase is optional or my monthly budget is already tight. Flexible payments should solve a timing problem, not hide an affordability problem. That is the line I would keep in mind before using the service.
Who should use it, and who should skip it
I think the app suits shoppers who plan purchases carefully, want to examine payment choices in one place, and can track future commitments without difficulty. It may be particularly helpful for a larger planned expense where paying everything at once would create a temporary cash-flow problem, but where the purchase itself is necessary and the schedule remains comfortable.
I would skip it for impulse buying, frequent small purchases, or any situation where I am already struggling to remember existing bills. I would also choose a regular payment method when the item is affordable today and I do not gain a meaningful benefit from spreading the cost. The app is not a substitute for a spending limit, and its convenience can work against me if I use it to justify purchases that do not fit my budget.
Age suitability is listed as Everyone, and the app is free to install. Those points make it easy to try, but they should not be confused with a recommendation for every financial situation. The important question is whether I can understand and manage the specific payment commitment attached to the purchase I am considering.
My performance verdict
After looking at the app through the lens of speed, demanding shopping moments, reliability, and device compatibility, I see Affirm as a focused payment companion rather than a complete shopping destination. Its strongest quality is the way it encourages me to examine a purchase through a flexible-payment lens before completing it. The experience is most useful when I arrive with a clear budget and a specific reason for needing flexibility.
Its main friction is also clear: flexible payments add another layer to my financial routine. I need to read the terms, track the schedule, recover carefully from any uncertain checkout response, and keep the commitment visible alongside other bills. People who want the simplest possible transaction may prefer a debit card or an already familiar credit-card statement.
Still, I can recommend giving it a careful look if you regularly make planned, higher-cost purchases and want a dedicated way to review payment options. The app has a mature presence, a free entry point, and broad adoption, while its current release supports a relatively modern device environment. I would use it deliberately, compare it with paying upfront, and confirm that the future payments fit my real budget.
My final view is positive but measured: Affirm: Buy now, pay over time is most valuable when it improves planning, not when it simply makes spending feel easier. Used with that mindset, it can make a large purchase more manageable and the decision more organized. Used without a budget, it can add commitments faster than I notice them. That difference comes down less to the app’s promise and more to the discipline I bring to each purchase.
Pros
- Flexible payment options for budgeting.
- Easy integration with various online stores.
- Quick approval process for credit.
- No hidden fees or upfront costs.
- User-friendly interface and navigation.
Cons
- Limited to partnered retailers only.
- Potential impact on credit score.
- High interest rates if payments are late.
- Not available internationally.
- Requires a soft credit check upfront.
FAQs for Affirm: Buy now, pay over time
What is Affirm and how does it work?
Affirm is a financial service app that allows users to make purchases and pay for them over time with transparent, flexible installment plans. Unlike traditional credit cards, Affirm provides clear payment terms without hidden fees. Users can select their preferred payment schedule at checkout and manage their plans directly through the app.
Are there any interest rates or fees associated with using Affirm?
Affirm does charge interest on some transactions, which can range from 0% to 30% APR, depending on the merchant and your credit profile. However, Affirm prides itself on transparency, so you'll know all costs upfront before you commit to a payment plan. There are no hidden fees, and late fees are generally not charged.
How do I qualify for an Affirm payment plan?
To qualify for an Affirm payment plan, users must be at least 18 years old (19 in Alabama or if you’re a ward of the state in Nebraska) and have a valid U.S. or APO/FPO/DPO address. Affirm performs a soft credit check to determine eligibility, which does not impact your credit score. Approval is based on your creditworthiness and other factors.
Where can I use Affirm to make purchases?
Affirm can be used at thousands of partner merchants across various categories, including travel, fashion, electronics, and home goods. Users can shop directly through the Affirm app or on websites of partnered retailers that offer Affirm as a payment option at checkout. New merchants are regularly added to Affirm’s network.
How does Affirm protect my personal information?
Affirm takes several measures to safeguard your personal information. The app uses encryption and security protocols to protect data transmission and storage. Affirm complies with all relevant regulations and employs security teams to monitor and protect against unauthorized access. Users can also enable additional security features like two-factor authentication for enhanced account protection.

Affirm: Buy now, pay over time
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@affirm.com, visit https://www.affirm.com, or review their https://www.affirm.com/privacy/.










